The Insurance Company Keeps Calling Me
The adjuster wants a statement, medical information, or answers about what happened. You're wondering what you should—and shouldn't—say.
 Free Case Review
Personal injury counsel · Zephyrhills, Florida
An accident can leave you with a lot more than an injury.
You don't have to know whether you have a “case” before you call us.
Just tell us what happened.
Treating clients like family since 1985. Personal injury lawyers serving Zephyrhills, Tampa Bay, and injured people throughout Florida.
Need help now? Call or text Drew directly: (813) 714-2018
SECTION 2 — WHAT ARE YOU WORRIED ABOUT RIGHT NOW?
Most people don't wake up after an accident thinking about lawsuits.
They're wondering:
Why am I still hurting?
How am I supposed to work like this?
Who is going to pay these medical bills?
Why does the insurance company keep calling me?
Is that settlement offer fair?
What if they're blaming me?
What if my injuries are worse than I thought?
How is all of this going to affect my family?
Those are the questions we want to help you answer.
Because before you can decide what to do about a personal injury claim, you need to understand what's happening—and what options you may have.
SECTION 3 — START WITH THE PROBLEM YOU'RE FACING
The adjuster wants a statement, medical information, or answers about what happened. You're wondering what you should—and shouldn't—say.
You've been offered money, but you don't know whether it accounts for your injuries, lost income, future treatment, and everything else the accident has cost you.
You need care, but you're worried about the bills—or you don't have health insurance at all.
You thought you'd feel better by now. Instead, days or weeks have passed and you're beginning to wonder whether something more serious is wrong.
Your paycheck stopped or got smaller. Your rent, mortgage, utilities, groceries, and other expenses didn't.
You've heard numbers from friends, insurance adjusters, advertisements, and the internet. But what actually determines the value of your claim?
The other driver—or their insurance company—says you caused some or all of the accident. That doesn't necessarily mean the conversation is over.
You were injured by someone who has little or no insurance. You may still have options for recovery.
You don't need to understand personal injury law before talking to a personal injury lawyer.
SECTION 4 — YOUR SITUATION MAY BE MORE COMPLICATED THAN IT LOOKS
Two people can be injured in similar accidents and face very different problems afterward.
Maybe you:
Your injury isn't just affecting your health. It's threatening your ability to earn a living.
The insurance company is pointing to an old injury, arthritis, or another condition and suggesting the accident didn't cause your problems.
The adrenaline wore off—and then the pain began.
There's no simple pay stub showing exactly how much income you've lost.
You're concerned that assumptions about motorcyclists may affect how people view the accident.
Now you're wondering whether the insurance company will use those words to argue that your pain was already there.
Your priority is your child's recovery. But you also need to understand who is responsible for the medical care and what the future may hold.
You're grieving while suddenly facing financial, legal, and practical questions you never expected to confront.
Your circumstances matter.
SECTION 5 — WHAT HAPPENS AFTER AN ACCIDENT?
You aren't supposed to know how an injury claim works.
But knowing what may happen next can make the process feel a lot less overwhelming.
Some injuries are obvious immediately. Others become clearer over days or weeks.
Understanding your injuries and following appropriate medical advice matters first.
There may be multiple insurance policies involved—and the insurance company investigating your claim has its own interests to protect.
Medical expenses may be only part of the picture.
An injury can also affect your income, ability to work, daily activities, family responsibilities, and future medical needs.
An early settlement can sound attractive when bills are piling up.
But once a claim is settled, you generally don't get to reopen it because your injury turned out to be more serious than expected.
You don't have to become an expert in Florida personal injury law.
You need enough information to make a good decision about your situation.
SECTION 6 — HOW HAS THE ACCIDENT CHANGED YOUR LIFE?
A personal injury claim isn't just about what happened in the collision.
It's also about what happened afterward.
Are you recovering—or getting worse?
Will you need therapy, injections, surgery, or long-term care?
Did you miss a few days?
Are you working through pain?
Or are your injuries preventing you from returning at all?
Are medical bills arriving?
Has your income dropped?
Are ordinary household expenses becoming harder to pay?
Are other people now driving you to appointments, caring for your children, doing household work you used to do, or worrying about what happens next?
Will you fully recover?
Will you be able to return to the same work?
Could the injury affect you months—or years—from now?
These are not side issues.
They are part of understanding what this accident has actually done to you.
SECTION 7 — COMMON QUESTIONS
Being accused of contributing to an accident does not automatically mean you have no claim. The facts—and the degree of responsibility—matter.
It depends on which insurance company is calling and what they're asking. Before giving a recorded statement or signing documents, understand why the information is being requested.
That happens. Some injuries and symptoms aren't obvious immediately after an accident. Don't assume that delayed symptoms automatically mean they aren't related.
A pre-existing condition does not necessarily mean a new accident couldn't make that condition worse. Your prior health and what changed after the accident can both matter.
Those words are common on imaging reports, particularly as people get older. The important question may be how you were functioning before the accident compared with afterward.
There isn't a legitimate website calculator that can tell you.
Factors can include the nature of your injuries, medical treatment, lost income, future medical needs, insurance coverage, disputed fault, and how the injury has affected your life.
There may be other potential sources of coverage depending on the circumstances, including your own insurance policy.
Some claims resolve relatively quickly. Others take longer because treatment is ongoing, fault is disputed, the injuries are serious, or the insurance company won't make a reasonable offer.
Have a different question?
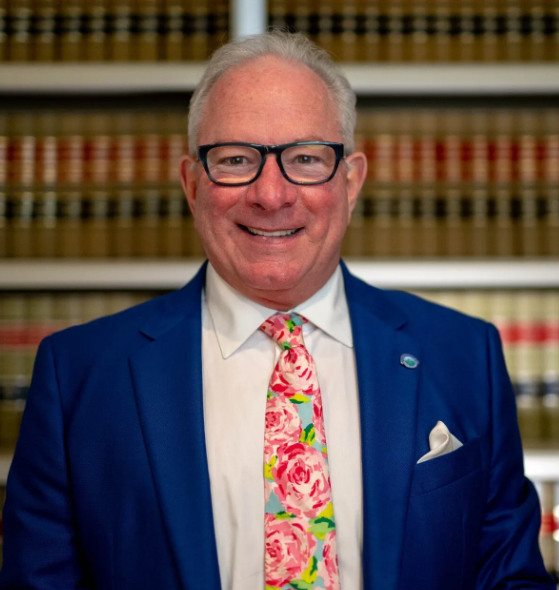
SECTION 8 — MEET DREW HUDGINS
When you're injured, you may be dealing with doctors, insurance adjusters, repair shops, employers, medical bills, and paperwork—all at the same time.
The last thing you need is another person who won't return your call.
Hudgins Law Firm has been treating clients like family since 1985.
For Drew Hudgins, that means listening to what happened, understanding how the accident has affected your life, explaining your options in plain English, and helping you make informed decisions about what comes next.
It's also why Drew makes his direct number available to clients and prospective clients.
SECTION 9 — WHAT KIND OF ACCIDENT WERE YOU IN?
Sometimes you know the problem you're trying to solve.
Other times, you simply want information about your type of accident.
From rear-end crashes to serious highway collisions.
Understanding the condition, the property, and your options after an unexpected fall.
Slip/Trip and Fall Accidents →Commercial vehicle crashes can involve serious injuries and complicated questions about responsibility.
Helping injured riders deal with serious injuries, insurance companies, and disputed fault.
When someone walking is struck by a vehicle, even a relatively low-speed collision can cause devastating injuries.
Helping injured cyclists understand their options after collisions with cars and other vehicles.
Uber and Lyft accidents may raise questions about which insurance coverage applies.
Serious injuries can change a person's ability to work, live independently, and care for a family.
Helping families understand their legal options after the preventable loss of someone they love.
“Knowing how nervous I was Drew put me at ease, never pressured me or made me feel uncomfortable.”
“The office staff really became my family throughout the whole process.They made me feel important from jump street.”
“His entire staff, especially Linda was always receptive and patient whenever I called and answered all my questions.”
You may not know whether you need a lawyer.
You may not know how serious your injury is going to be.
You may not know whether the insurance company's offer is fair.
You may not even know what questions you should be asking.
That's okay. Start with what you do know: what happened to you.
Tell us about the accident, what's happened since, and what you're worried about now.
We'll help you understand what may come next.
Or call or text Drew directly: (813) 714-2018
No pressure. No obligation. Just a conversation about your situation and your options.