Yesterday, you were driving to work, picking up your kids, heading home, or going about an ordinary day.
 Free Case Review
Personal injury counsel · Zephyrhills, Florida
Hurt in a Car Accident?
You Probably Have a Lot of Questions.
Then someone hit you.
Now your car may be damaged. You're hurting. The insurance company wants answers. You're missing work. Medical appointments are taking over your schedule.
And you may have no idea what you're supposed to do next.
You don't need to have everything figured out before you talk with us.
Start by telling us what happened.
Treating clients like family since 1985. Helping people injured in car accidents in Zephyrhills, Tampa Bay, and throughout Florida.
SECTION 1 — THE ACCIDENT ENDED. THE PROBLEMS DIDN'T.
A Few Seconds on the Road Can Disrupt Months of Your Life
At the accident scene, you may have been focused on the immediate problems.
Is everyone okay?
Can I drive my car?
Do we need an ambulance?
Should I call the police?
Then you went home.
And a different set of problems began.
Your neck started hurting.
You couldn't sleep.
The repair shop gave you an estimate.
An insurance adjuster called.
You had to tell your boss you couldn't come in.
A doctor ordered more tests.
A medical bill arrived.
Suddenly, a crash that lasted a few seconds is affecting your health, your job, your finances, your family, and your plans.
That's the part of a car accident people don't expect.
SECTION 2 — “I FELT OKAY AT FIRST. NOW I DON'T.”
Some Injuries Don't Fully Reveal Themselves at the Accident Scene
After a collision, people sometimes say:
“I'm okay.”
“I'm just shaken up.”
“My back's a little sore.”
And they may sincerely believe it.
But your body has just experienced a violent event. Once the shock and adrenaline subside, symptoms can become more noticeable.
You may develop:
- neck pain and stiffness,
- back pain,
- headaches,
- shoulder pain,
- numbness or tingling,
- dizziness,
- difficulty concentrating,
- knee or leg pain,
- or other symptoms that weren't obvious immediately.
Other injuries can be more serious, including herniated discs, fractures, traumatic brain injuries, spinal injuries, and injuries that eventually require surgery.
That's why the question isn't simply:
“Were you hurt at the scene?”
It's also:
“What has happened to you since?”
SECTION 3 — WHAT ARE YOU WORRIED ABOUT RIGHT NOW?
Start With the Problem That's Keeping You Up at Night
Not every person injured in a car accident has the same problem.
Which of these sounds most like yours?
The Insurance Company Keeps Calling Me
An adjuster wants a statement or keeps asking questions, and you're afraid of saying something that could hurt your claim.
The Settlement Offer Seems Too Low
The insurer has offered money, but you don't know whether it's fair—or what happens if your injuries get worse after you accept it.
I Need Medical Treatment I Can't Afford
You need treatment, but the cost is making you wonder whether you can keep going to the doctor.
My Pain Isn't Getting Better
You expected soreness. You didn't expect to still be hurting weeks later.
I Missed Work and the Bills Are Piling Up
Your income has dropped at exactly the same time your accident has created new expenses.
I Don't Know What My Case Is Worth
You want a realistic explanation of what actually determines the value of a car accident claim.
I'm Being Blamed for the Accident
The other driver—or their insurance company—says you caused the crash.
The Other Driver Doesn't Have Insurance
The person who hit you doesn't have enough coverage—or may not have insurance at all.
SECTION 4 — THE INSURANCE COMPANY IS ALREADY WORKING ON THE CLAIM
Their Investigation May Begin Before You Know How Badly You're Hurt
You may still be figuring out how to get your car repaired.
The insurance company may already be investigating.
An adjuster might ask you for:
- your version of how the crash occurred,
- a recorded statement,
- photographs,
- information about your injuries,
- medical records or authorizations,
- repair information,
- or other documentation.
That doesn't necessarily mean the insurance company is doing something improper.
Investigating claims is what insurance companies do.
The problem is that you're being asked for information at a time when you may not know:
- the full extent of your injuries,
- how much treatment you'll need,
- how much work you'll miss,
- whether you'll completely recover,
- or what the accident will ultimately cost you.
The insurer may be ready to evaluate your claim.
You may not be ready to evaluate your injuries.
That's an important difference.
SECTION 5 — “THE OTHER DRIVER SAYS IT WAS MY FAULT”
What Happened May Not Be as Clear as the Other Driver Claims
At the accident scene, two drivers can have very different versions of the same collision.
Maybe the other driver says you changed lanes.
You say they were speeding.
They say the light was green.
A witness remembers something different.
Or perhaps you believe you did make a mistake—but you also believe the other driver contributed to what happened.
Don't assume an accusation at the scene determines the outcome of a claim.
Evidence may include:
- photographs,
- vehicle damage,
- witness accounts,
- crash reports,
- video,
- physical evidence,
- electronic information,
- and other facts surrounding the collision.
Florida's comparative-fault rules can also make shared responsibility relevant to the amount an injured person may potentially recover.
The important question isn't simply who pointed the finger first.
It's what the evidence shows.
SECTION 6 — “WHO IS GOING TO PAY THESE MEDICAL BILLS?”
The Financial Problems Can Start Before You Recover
Emergency care.
Diagnostic imaging.
Specialists.
Physical therapy.
Prescriptions.
Injections.
Follow-up appointments.
Potential surgery.
The cost of an injury can add up quickly.
And while those bills are arriving, you may be earning less because the injury is keeping you from working.
That's what makes the financial aftermath of a car accident so difficult.
Expenses can go up at the same moment income goes down.
Depending on the circumstances, a car accident claim may involve issues such as medical expenses, lost income, future treatment needs, pain and suffering, reduced earning capacity, and other losses.
But understanding the impact of an accident means looking beyond a stack of medical bills.
What has this accident actually changed about your life?
SECTION 7 — “I CAN'T KEEP MISSING WORK”
An Injury Can Threaten the Income Your Family Depends On
Maybe you've already missed a few shifts.
Maybe you've been out for weeks.
Maybe you've tried to return, but the pain makes it impossible to perform your normal duties.
Or your doctor has given you restrictions your employer can't accommodate.
Now you're wondering:
How long can I afford to be out?
How long will my employer wait?
What if I can't do my old job anymore?
What happens to my family if my income doesn't come back?
Lost income can be an important part of a car accident claim.
And if an injury creates permanent limitations that affect your ability to work in the future, the financial consequences may extend much further than the paychecks you've already missed.
SECTION 8 — WHAT IF I ALREADY HAD BACK OR NECK PROBLEMS?
An Old Condition Doesn't Tell the Whole Story
Maybe you had back pain before the crash.
Maybe you've been treated for your neck in the past.
Maybe your MRI contains words like:
“degenerative changes.”
Now the insurance company is asking about your medical history, and you're worried they'll say:
“This wasn't caused by the accident.”
Pre-existing conditions can make an injury claim more complicated.
But an important question is often:
What changed?
Were you working normally before the crash?
Were you able to exercise, drive, sleep, care for your family, or go about your daily activities?
What symptoms appeared or became worse afterward?
Your medical history matters.
So does the difference between your life before the accident and after it.
SECTION 9 — WHAT IF THE OTHER DRIVER DOESN'T HAVE ENOUGH INSURANCE?
The Other Driver's Policy May Not Be the End of the Investigation
You discover the driver who hit you has no insurance.
Or they have insurance, but their coverage may not be enough for the injuries they caused.
It's easy to assume:
“Then there's nothing I can do.”
That isn't necessarily the conclusion.
Depending on the facts and the insurance policies involved, there may be other coverage that needs to be investigated, including potentially uninsured or underinsured motorist coverage.
The important thing is not to stop asking questions simply because the person who caused the collision appears to have inadequate coverage.
SECTION 10 — HOW MUCH IS MY CAR ACCIDENT CASE WORTH?
There Isn't an Honest One-Size-Fits-All Answer
You may have seen advertisements promising huge settlements.
A friend may tell you what someone they know received.
You may even find websites offering an instant “case value calculator.”
But two crashes that look similar can affect two people very differently.
The value of a car accident claim may depend on factors such as:
- how the collision occurred,
- whether responsibility is disputed,
- the nature and severity of the injuries,
- the medical treatment required,
- whether additional treatment will be necessary,
- time missed from work,
- future earning limitations,
- the effect on daily life,
- whether injuries are permanent,
- available insurance coverage,
- and other circumstances unique to the person and the accident.
A broken leg for someone who works behind a desk may have one impact.
The same injury for someone who climbs ladders for a living may have another.
The injury matters.
So does the life the injury happened to.
SECTION 11 — WHAT IF THE INSURANCE COMPANY ALREADY OFFERED ME MONEY?
The Number Isn't the Only Thing You Need to Evaluate
When bills are accumulating, a settlement check can look like an answer.
Before deciding, however, you need to understand the question you're being asked to settle.
Do you know the full extent of your injuries?
Have you finished treatment?
Could you need additional care?
Are you back at work?
Could your injuries affect your ability to earn money in the future?
What exactly are you agreeing to release in exchange for the payment?
Once a claim is finally settled, you generally don't get another opportunity to ask for more because your medical condition later turned out to be worse than expected.
Don't evaluate only what they're offering you today.
Consider what the accident may cost you tomorrow.
SECTION 13 — WHAT DOES A CAR ACCIDENT CLAIM ACTUALLY INVOLVE?
Most Claims Develop in Stages
Every case follows its own path, but the process may involve:
1. Understanding What Happened
The circumstances of the crash and available evidence are reviewed.
2. Understanding Your Injuries
Medical treatment helps establish what was injured and what recovery may look like.
3. Identifying Available Insurance
The relevant policies and potential sources of coverage need to be understood.
4. Measuring the Impact
Medical expenses are only part of the picture. Lost income, future treatment, permanent limitations, and the effect on everyday life may also matter.
5. Dealing With the Insurance Company
Information is exchanged and the claim may eventually enter settlement negotiations.
6. Deciding Whether a Settlement Is Fair
Some claims resolve through negotiation. Others cannot be fairly resolved without litigation.
You don't need to memorize that process.
That's the lawyer's job.
Your job is to focus on getting your life back.
SECTION 14 — TALK TO DREW
You Don't Need to Know Whether You Have a “Good Case” Before You Call
Maybe you're not sure how badly you're injured.
Maybe you're worried that you were partly responsible.
Maybe the insurance company has already called three times.
Maybe you're missing work.
Maybe someone has already offered you money.
Or maybe you're simply overwhelmed by all of it.
Start there.
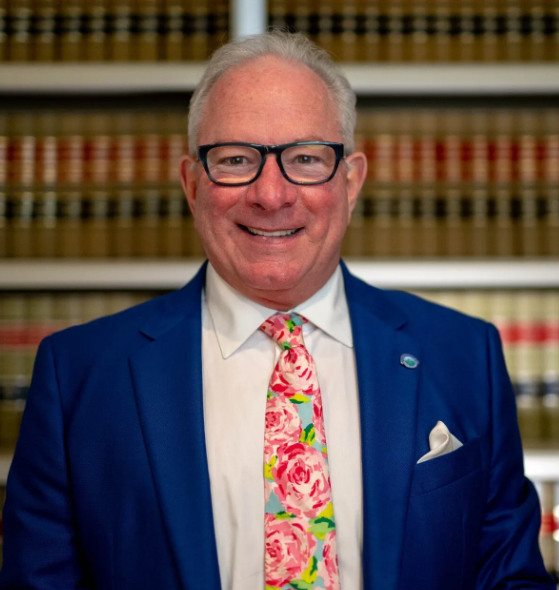
Tell Drew what happened and what's worrying you now.
Hudgins Law Firm has been treating clients like family since 1985. Drew Hudgins can help you understand the insurance and injury-claim process, what issues may matter in your particular situation, and what your next steps could be.
You don't need to arrive with the right legal terminology.
You just need to tell us what happened.
Call or text Drew directly: (813) 714-2018
Frequently Asked Questions After a Florida Car Accident
Do I need a lawyer after every car accident?
No. Not every collision requires an attorney. But if you've been injured, are missing work, face significant medical treatment, are being blamed, have been offered a settlement, or simply don't understand what the insurer is doing, getting legal advice may help you understand your options.
What if I didn't go to the hospital from the accident scene?
Not every injury is immediately obvious, and not everyone goes directly to an emergency room. If you're experiencing symptoms, the important issue is your health. Seek appropriate medical attention and accurately explain when and how your symptoms developed.
What if my pain didn't start until several days later?
Symptoms can sometimes become more noticeable after the initial shock of a collision has passed. Delayed symptoms don't automatically establish or disprove whether an injury is accident-related. Medical evaluation and the particular facts matter.
Should I give the insurance company a recorded statement?
That can depend on which insurance company is requesting it, the applicable policy, and the circumstances. Before agreeing, understand who is asking, why they want it, and what obligations you may have.
What if the accident was partly my fault?
Florida follows a modified comparative-negligence system. Responsibility can be divided among parties, and a person's percentage of fault can affect recovery. If fault is disputed, the specific facts and evidence are important.
Who pays my medical bills after a Florida car accident?
Florida's no-fault insurance system generally makes Personal Injury Protection (PIP) coverage an important starting point for accident-related medical expenses and certain lost income, subject to policy terms and Florida law. Serious injury claims can involve additional issues and potential sources of recovery.
What if the driver who hit me doesn't have insurance?
Other possible coverage may need to be investigated, including uninsured or underinsured motorist coverage if applicable. Don't assume the absence of adequate insurance on the other vehicle automatically means there are no options.
Can I recover money for work I've missed?
Lost income may be relevant when an accident-related injury prevents you from working. The type of documentation required can vary depending on whether you're salaried, hourly, commissioned, self-employed, or otherwise compensated.
How much is my car accident claim worth?
There isn't a reliable answer based solely on the type of accident. Injuries, treatment, lost income, future needs, permanent limitations, responsibility for the crash, available coverage, and the effect on your life can all matter.
How long does a car accident claim take?
Some claims can be resolved relatively quickly. Others take longer because medical treatment is continuing, the extent of the injuries remains uncertain, responsibility is disputed, insurance coverage is complicated, or the parties cannot agree on a fair resolution.
Should I accept the insurance company's settlement offer?
Before accepting, understand what the settlement covers, what rights you're releasing, whether your medical condition is sufficiently understood, and whether future losses have been considered.
How long do I have to file a car accident lawsuit in Florida?
Florida law imposes deadlines on personal injury lawsuits, and determining the applicable deadline can depend on the facts and type of claim. Waiting can also make evidence more difficult to preserve. If you're concerned about a deadline, it's better to get advice based on your specific accident than rely on a general website rule.